Opportunities
Opportunities, priced with their risks
Decision-oriented material for investors and dealmakers. Every brief carries its risk factors in the same document as its thesis, not in a separate disclaimer.
Sector opportunity briefs
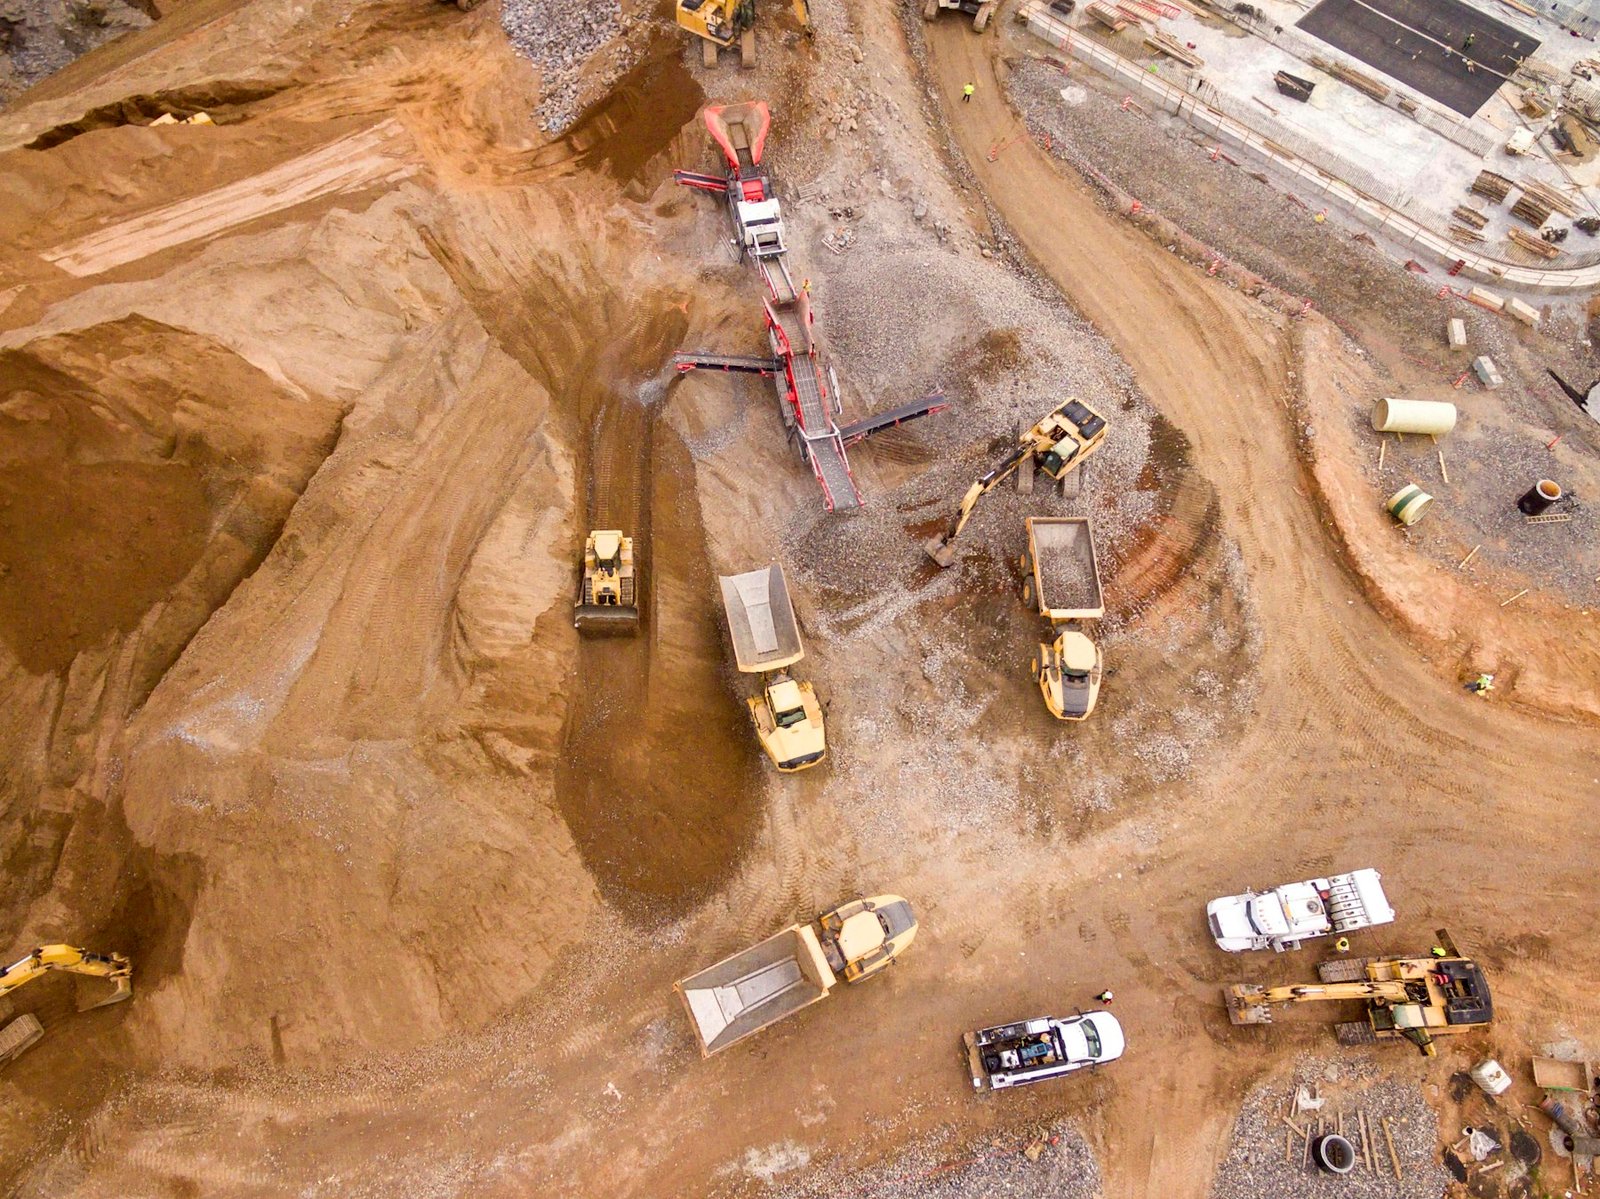
Georgia, USA · Shane McLendon · Unsplash Licence
miningDownstream lithium processing
Export restrictions on unprocessed ore create a captive feedstock position for anyone who can build and power a processing facility. The constraint is energy and capital cost, not resource access.
- Market size
- Export value has moved between roughly US$70m and US$620m a year since 2021, dominated by price rather than volume.
- Regulatory path
- Mining title through the Ministry of Mines; investment licensing through ZIDA; environmental authorisation through EMA. Special Economic Zone incentives may apply depending on siting.
- Principal risk
- Power availability is the binding constraint on any processing investment.
Location not stated · Andrew Van Hofwegen · Unsplash Licence
manufacturingIndependent power generation
Every industrial constraint in the country routes back to electricity. Independent generation addresses the binding constraint directly, and industrial offtakers have demonstrated willingness to pay a premium for reliability.
- Market size
- Access is measured at roughly 62% of population, but that measures connection rather than supply. The addressable gap is reliability, not connection.
- Regulatory path
- Generation licence through ZERA; investment licensing through ZIDA; grid connection and wheeling agreements negotiated with the utility.
- Principal risk
- Offtaker credit quality, particularly where the counterparty is the state utility.
Rutendo Petros · Unsplash Licence
agricultureAgro-processing and cold chain
Zimbabwe exports agricultural output in largely unprocessed form and imports processed food. Closing part of that loop is an import-substitution play with a domestic demand base rather than an export bet.
- Market size
- Agriculture is roughly 9–10% of GDP but a far larger share of employment, implying substantial unprocessed volume.
- Regulatory path
- Investment licensing through ZIDA; food safety and standards through relevant authorities; export certification where applicable.
- Principal risk
- Rainfall variance drives input availability year to year.
Other modules
Project & deal tracker
Publicly announced investments, JVs, privatisations and tenders — aggregated with source links, not editorialised.
Regulatory & licensing guides
ZIDA processes and sector-specific permitting, with where applications realistically stall.
Risk register
7 structural risks, reviewed and dated. The section that most differentiates ZIX from official messaging.